Georgia's Income Tax Rate Is 4.99% for 2026: What Changed, the $15,000 and $30,000 Standard Deductions, and a $50,000 Worker's Math
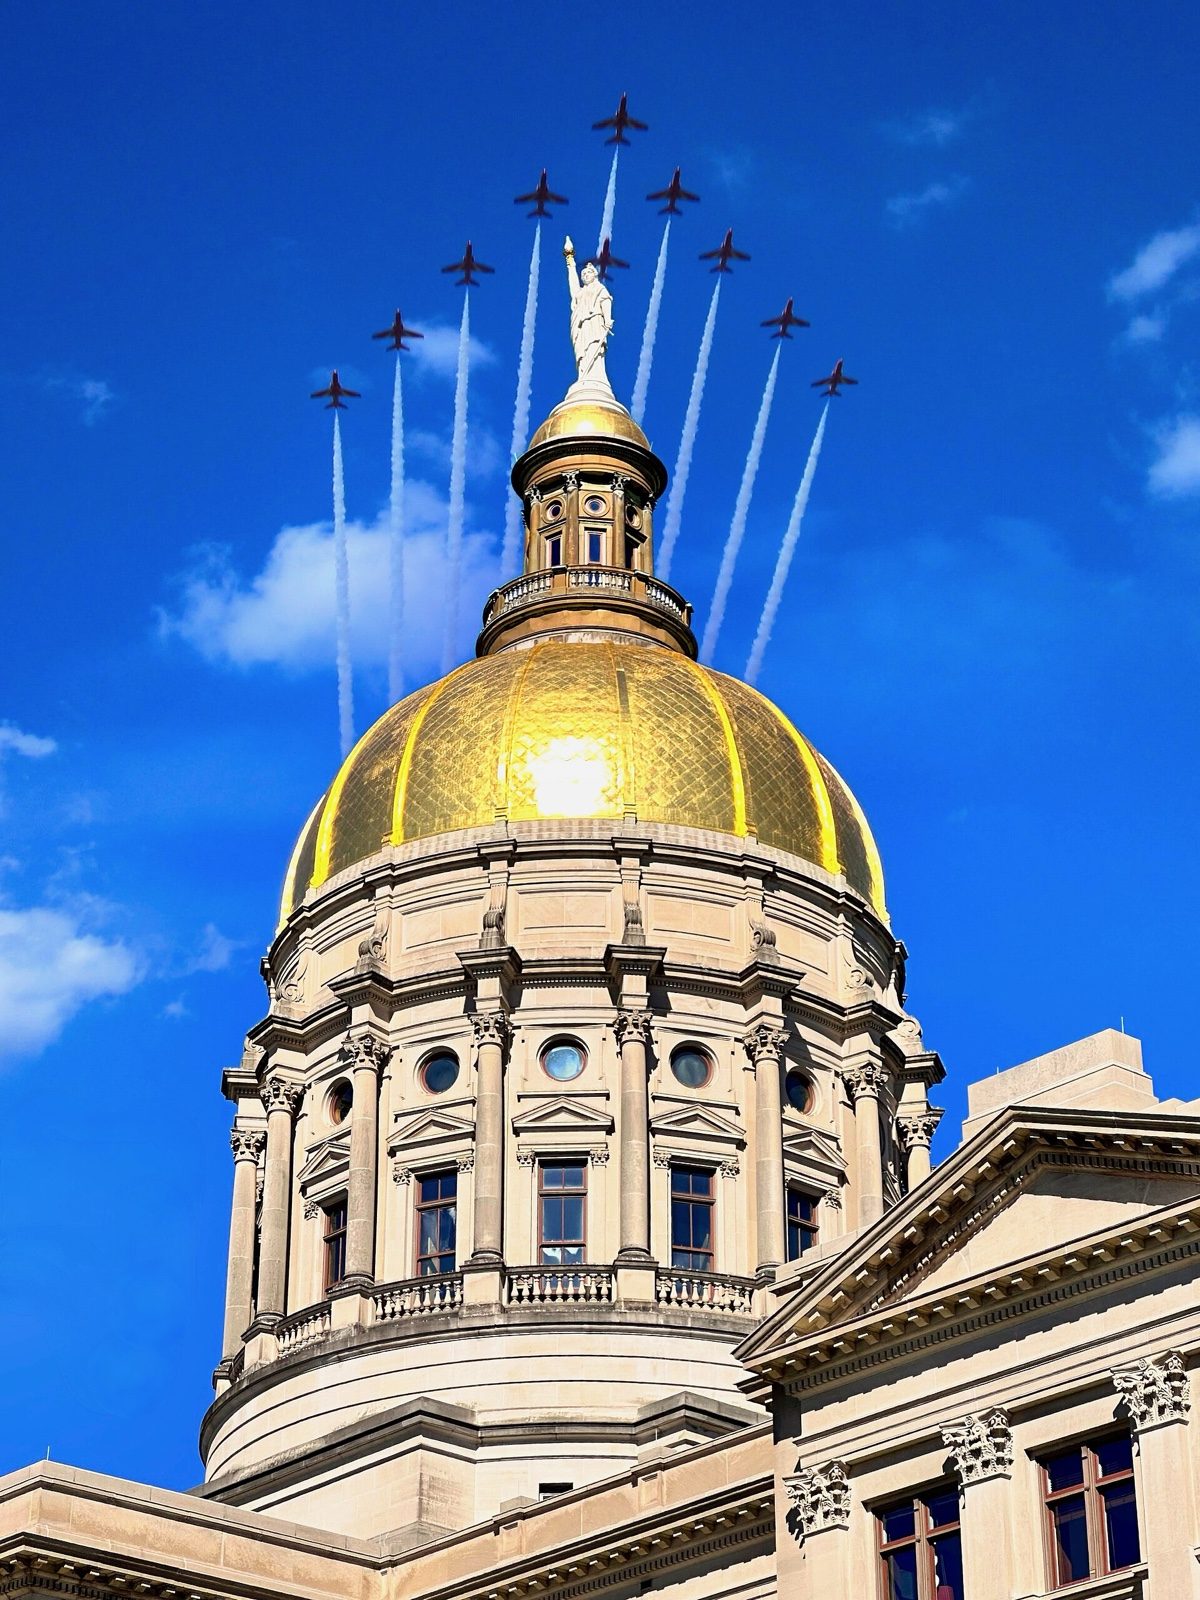
Georgia's income tax rate is 4.99% for 2026. Shown: the gold dome of the Georgia State Capitol in Atlanta (file photo). Photo: Harrison Keely / Wikimedia Commons (CC BY 4.0)
COLUMBUS, Ga. - Georgia's individual income tax rate is 4.99% for 2026, down from 5.19%, and the state's standard deduction is $15,000 for single filers and $30,000 for married couples filing jointly, according to the Georgia Department of Revenue. For a hypothetical single filer earning $50,000, subtracting the $15,000 standard deduction leaves $35,000 in taxable income, producing $1,746.50 in state income tax at the new rate before other adjustments. The changes are part of House Bill 463, signed by Gov. Brian Kemp on May 11, 2026, with the rate reduction effective Jan. 1, 2026.
The legislation also addresses retirement income, qualified overtime pay, cash tips and certain tax credits and exemptions, according to the governor's official announcement. The Department of Revenue has published updated information explaining the rate and standard deductions. The following examples illustrate the arithmetic using those published figures and do not represent individualized tax advice.
1. Georgia's Income Tax Rate Drops From 5.19% to 4.99%
Georgia's flat individual income tax rate decreased from 5.19% to 4.99% for 2026, according to the Department of Revenue. The change represents a reduction of 0.20 percentage points, or $2 for each $1,000 of taxable income. The effective date is Jan. 1, 2026, as specified in the governor's May 11 announcement concerning HB 463.
The governor signed nine bills on May 11, including HB 463, according to the official announcement. That legislation lowered the income tax rate and provided for further annual rate reductions. The announcement described the 2026 reduction as bringing Georgia's rate below 5% three years ahead of the schedule previously established.
The 4.99% rate applies to taxable income rather than automatically applying to every dollar of wages. The standard deduction and any other applicable deductions or exclusions can affect the income amount subject to taxation. The Department of Revenue's published rate and deduction figures provide the basis for the examples below.
2. Standard Deductions Are $15,000 or $30,000
Georgia's Department of Revenue lists a $15,000 standard deduction for single filers, heads of households and married individuals filing separately. Married couples filing jointly have a $30,000 standard deduction. These figures are listed on the department's Important Tax Updates page.
| Filing status | Standard deduction |
|---|---|
| Single | $15,000 |
| Head of household | $15,000 |
| Married filing separately | $15,000 |
| Married filing jointly | $30,000 |
The standard deduction reduces the amount of income included in the basic taxable-income calculation. For example, a single filer with $50,000 in wages would subtract the $15,000 standard deduction to arrive at $35,000 before considering other applicable adjustments. A married couple filing jointly with $100,000 would subtract $30,000, leaving $70,000 in the corresponding simplified calculation.
The filing-status distinction matters because the standard deduction is not identical for every return. According to the Department of Revenue, the $30,000 amount applies to married taxpayers filing jointly, while the other listed filing statuses receive $15,000. The deduction amounts are separate from the statewide 4.99% tax rate.
3. Example: What a $50,000 Worker Would Pay
Consider a hypothetical single taxpayer earning $50,000 in annual wages and taking Georgia's $15,000 standard deduction. The following calculation uses the 4.99% state tax rate published by the Department of Revenue. It is an illustration only and does not account for other credits, deductions or adjustments.
Example calculation:
- Annual wages: $50,000
- Standard deduction: $15,000
- Taxable income: $50,000 - $15,000 = $35,000
- Tax at 4.99%: $35,000 x 0.0499 = $1,746.50
- Tax at former 5.19% rate: $35,000 x 0.0519 = $1,816.50
- Difference attributable to rate change: $70.00
The calculation produces $1,746.50 at the new rate compared with $1,816.50 using the former rate on the same $35,000 taxable-income amount. The difference is $70.00, calculated by applying the 0.20-percentage-point rate reduction to $35,000. This comparison isolates the rate change and does not attempt to calculate the taxpayer's complete return.
The comparison holds taxable income constant at $35,000 for both rates. That approach separates the financial effect of the rate reduction from other provisions of HB 463. Actual tax liability can differ when additional deductions, exclusions or credits apply.
4. Example: Married Couple Earning $100,000
The Department of Revenue's $30,000 standard deduction also permits a simplified calculation for married taxpayers filing jointly. Consider a hypothetical married couple with $100,000 in combined income using that deduction. The example applies the same 4.99% state income tax rate without including other possible adjustments.
Example calculation:
- Combined income: $100,000
- Standard deduction: $30,000
- Taxable income: $100,000 - $30,000 = $70,000
- Tax at 4.99%: $70,000 x 0.0499 = $3,493.00
The resulting illustrative state income tax is $3,493.00. That figure comes from multiplying $70,000 in taxable income by the 4.99% rate. It is not a prediction of the amount any particular couple will owe after all applicable tax provisions are considered.
Both illustrations apply the standard deductions associated with their respective filing statuses. The first uses $15,000 for a single filer, while the second uses $30,000 for married taxpayers filing jointly. Both use the same flat income tax rate published for 2026.
5. Qualified Overtime and Cash Tips Receive Separate Treatment
HB 463 also created temporary Georgia income tax exclusions for qualified overtime pay and cash tips through 2028, according to the governor's May 11 announcement. The Department of Revenue explains that Georgia did not adopt the federal overtime and tipped-wage exemptions. Instead, the state provides exclusions of up to $1,750 for each qualifying category.
The amounts represent potential exclusions from taxable net income rather than automatic tax payments or refunds. The Department of Revenue identifies separate amounts for qualified overtime and cash tips. Whether a taxpayer can use an exclusion depends on having qualifying income under the applicable provisions.
Illustrative maximum tax effects at 4.99%:
- Qualified overtime exclusion: $1,750
- Cash tips exclusion: $1,750
- One category: $1,750 x 0.0499 = $87.33
- Both categories: $3,500 x 0.0499 = $174.65
The $87.33 example reflects the rounded tax effect of one maximum $1,750 exclusion at the 4.99% rate. The $174.65 example assumes both maximum exclusions apply, reducing taxable income by a combined $3,500. These calculations illustrate potential tax effects only for taxpayers with qualifying amounts.
The governor's announcement identifies these exclusions as temporary provisions through 2028. The Department of Revenue distinguishes Georgia's treatment of overtime and tips from the federal approach. The examples above use the maximum amounts stated in the department's guidance rather than assuming that every worker qualifies.
6. Retirement Income and Other Changes in HB 463
The income tax rate reduction is one component of the legislation signed May 11. According to the governor's announcement, HB 463 also increases the retirement income exclusion to $70,000 beginning in 2027. That provision has a different effective year from the 2026 reduction in the general income tax rate.
The legislation also provides for further annual income tax rate reductions, according to the governor's release. It includes changes involving certain tax credits and sales tax exemptions. The announcement identifies these measures as part of the broader legislation alongside the standard deduction increase and the temporary overtime and cash-tip exclusions.
The governor's May 11 announcement also identified other legislation addressing different areas of taxation. Senate Bill 33 concerns a Local Homestead Option Sales Tax intended to provide homeowner relief. House Bill 445 allows business owners to appeal reassessments involving certain high-value tangible personal property.
Those measures are distinct from the individual income tax examples calculated using HB 463. The Department of Revenue's 4.99% figure establishes the rate used in the wage and married-filing examples. The governor's announcement separately describes the retirement exclusion, temporary exclusions and additional legislative changes.
7. Where Georgia Publishes Its Tax Updates
The Georgia Department of Revenue maintains an Important Tax Updates page at dor.georgia.gov. That official resource identifies the 4.99% flat rate, the standard deductions and the state's treatment of overtime and cash tips. The governor's official website, gov.georgia.gov, also published the May 11 announcement describing HB 463 and the other bills signed that day.
The Department of Revenue previously reported that it began processing 2025 tax returns on Feb. 2, 2026, with an April 15, 2026, filing deadline for that tax year. Those dates apply to the earlier filing season rather than establishing deadlines for the 2026 income tax year. The 4.99% rate discussed in this article took effect Jan. 1, 2026.
For the two hypothetical income examples, the central figures remain $1,746.50 for a single filer with $50,000 in wages and $3,493.00 for married taxpayers filing jointly with $100,000 in income. Both figures use the Department of Revenue's 4.99% rate and applicable standard deductions in simplified calculations. Neither example includes additional credits, deductions or other adjustments that could change an individual return.
Source: Georgia Department of Revenue tax updates (dor.georgia.gov); Office of Gov. Brian Kemp, May 11, 2026 announcement
News organizations may republish this story with credit. See our guidelines.
Know someone who'd want to read this? Email it to a friend.
Own a Columbus business? 20,000+ page views in 30 days. Ads from $125/month. See ad options Follow Columbus Times on FacebookLocal news, events and people, in your feed every day.Most read this week
- Phenix City and Russell County Voters See School Taxes Again Nov. 3: 4 Mills and 4.5 Mills
- Fort Benning Ceremony Calendar: 12 Graduations, 20 Turning Green Events and 2 Turning Blue Ceremonies Through Dec. 17
- Georgia's 3 Amendments: Which Will Pass, Who's Against Them, and What Happens If They Fail
- Georgia's 3 Constitutional Amendments on the Nov. 3 Ballot, Explained in Plain English
- Veterans Day 2026 in Columbus: Free Meals, Deals and Events Honoring Those Who Served
More stories
 Finance What Columbus Earns: Median Household Income in Every Columbus ZIP Code, From $32,401 to $114,468
 Finance Why So Many Americans Feel Broke Even When They Earn $100,000 a Year
 Finance How Much Money Do You Need to Be Considered Rich in Columbus, Georgia?
 Finance 7 Georgia Benefits Many Eligible Residents May Be Missing
Comments
Be respectful. No personal attacks, hate speech, spam or anyone's private information. Every comment is reviewed before it appears. Comment rules
No comments yet. Be the first to share your thoughts.