Why So Many Americans Feel Broke Even When They Earn $100,000 a Year
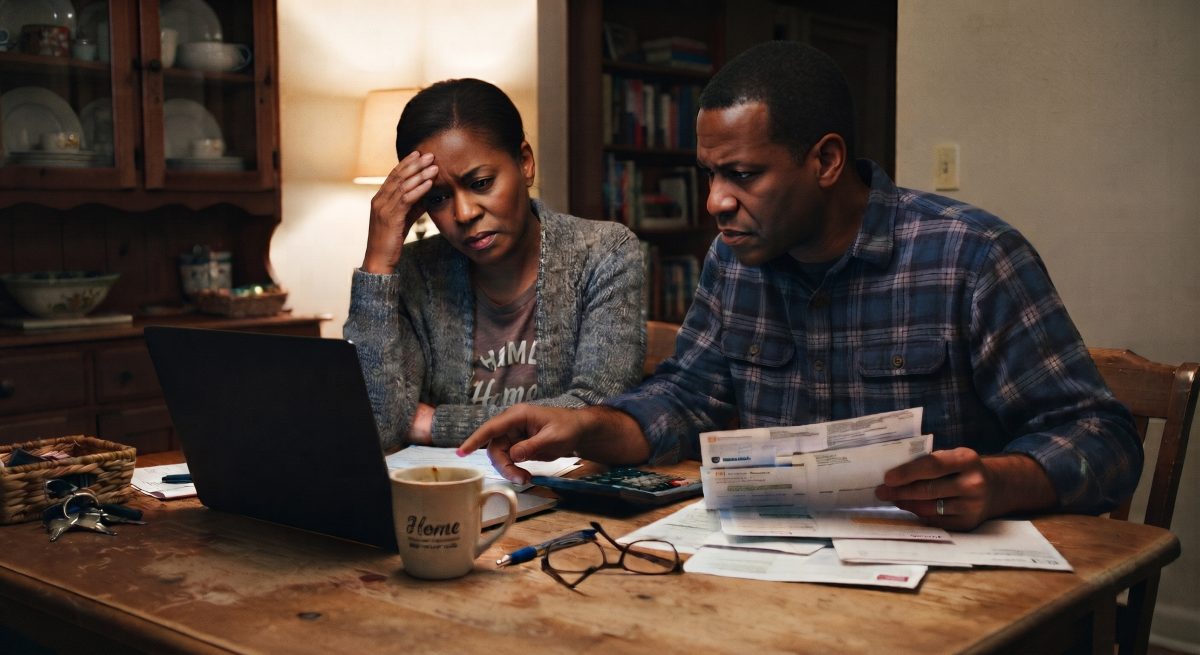
Even households earning a six-figure salary can find themselves facing tight budgets and financial strain as the costs of housing, childcare, and everyday expenses continue to rise.
Earning $100,000 a year used to represent a major financial milestone for American workers. It suggested a comfortable home, reliable transportation, family vacations, and enough savings to handle unexpected expenses. But in 2026, a six-figure salary does not necessarily provide the financial security many people expect.
Across the country, households earning what was once considered an upper-middle-class income are discovering that their paychecks disappear faster than anticipated. Housing, insurance, groceries, transportation, and childcare can consume thousands of dollars before families spend anything on entertainment or vacations. Even in relatively affordable communities such as Columbus, Georgia, earning $100,000 does not automatically mean having money left over.
$100,000 Is Not What It Used to Be
According to the U.S. Bureau of Labor Statistics, consumer prices increased 3.7% during the 12 months ending in September 2026. Energy prices increased 20.4%, while gasoline prices climbed 34.2% over the same period. These increases add pressure to household budgets already affected by several years of rising living costs.
The problem extends beyond the latest inflation figures because earlier price increases remain embedded in everyday expenses. Inflation slowing does not mean groceries, insurance, or housing return to their previous prices. For families whose earnings have not increased enough to offset cumulative price increases, maintaining the same standard of living can require spending a larger portion of their income.
What a $100,000 Salary Actually Looks Like
A salary of $100,000 equals approximately $8,333 per month before taxes and payroll deductions. After federal income taxes, Social Security, Medicare, health insurance, and retirement contributions, the amount available for household expenses can be substantially lower. The actual figure depends on filing status, dependents, benefit elections, and other circumstances.
Consider a hypothetical family with $6,200 in monthly take-home pay. Their budget might look like this:
Monthly expense Amount Mortgage or rent $1,900 Car payments, gas, and insurance $950 Groceries and household supplies $850 Healthcare expenses $450 Childcare $900 Utilities, internet, and phones $400 Debt payments $350 Clothing and miscellaneous expenses $400 Total monthly expenses $6,200 Money remaining $0
This is an illustrative household budget, not a survey of actual Columbus expenses or a calculated tax estimate.
This family is not necessarily living extravagantly, yet virtually its entire take-home income is committed to regular expenses. An unexpected vehicle repair, medical bill, or home maintenance problem could require using savings or borrowing money. The household earns six figures but has little flexibility to absorb financial setbacks.
Housing and Transportation Take the Biggest Bite
Housing and transportation account for more than half of average American household spending, according to the Bureau of Labor Statistics. In 2024, households spent an average of $26,266 annually on housing and $13,318 on transportation. Combined, those two categories cost approximately $3,299 per month, although individual households may spend considerably more or less.
For residents of Columbus and neighboring Phenix City, transportation is particularly important because many households depend on personal vehicles for work, school, and everyday errands. Car payments are only part of the expense, with insurance, fuel, maintenance, and repairs adding hundreds of dollars to monthly budgets. Families maintaining two vehicles can face substantial transportation costs even when they avoid luxury models.
The Columbus Perspective: $100,000 Is Still a High Income
The U.S. Census Bureau reports that Columbus had a median household income of $58,073 during the 2020–2024 measurement period. A household earning $100,000 makes approximately 72% more than that figure, placing it well above the local median. That difference matters because financial pressure at $100,000 should not be confused with the more severe challenges many lower-income households face.
Nevertheless, higher earnings often come with additional financial obligations, particularly for families raising children or supporting relatives. A household earning $100,000 with three children, two car payments, and significant debt may have less disposable income than a child-free household earning $70,000. Income alone does not reveal how much financial flexibility a family actually possesses.
Even High Earners Can Lack Emergency Savings
The Federal Reserve’s May 2026 report on household financial well-being found that 63% of American adults could cover an unexpected $400 expense using cash or its equivalent. That leaves 37% who would need another approach or could not cover the expense, although these figures represent adults across all income levels. The report also found that only 35% of non-retirees believed their retirement savings plans were on track.
These findings illustrate the difference between earning money and building financial security. A household can maintain a respectable income while carrying substantial debt, saving little, and depending on every paycheck to meet its obligations. Financial stability depends partly on what remains after expenses, not simply the amount appearing on a paycheck.
Why a Raise Doesn’t Always Solve the Problem
Higher earnings can improve financial stability, but additional income sometimes disappears into larger financial commitments. Families may purchase more expensive homes, replace older vehicles, increase discretionary spending, or take on additional debt as their incomes rise. Economists and financial advisers commonly describe this pattern as lifestyle inflation.
Not every increase in spending reflects unnecessary consumption, however. A new child, higher insurance premiums, medical expenses, or supporting an aging parent can absorb additional income without improving a family’s lifestyle. Distinguishing unavoidable expenses from optional spending is essential when evaluating why a seemingly generous salary feels insufficient.
What Families Can Do Differently
For households feeling financially stretched, the biggest opportunities often involve examining large recurring expenses rather than eliminating occasional small purchases. Housing costs, vehicle ownership, insurance premiums, and high-interest debt can have far greater effects on financial stability than entertainment subscriptions or restaurant visits. Comparing insurance policies, avoiding unnecessary vehicle upgrades, and reducing expensive debt may create meaningful breathing room.
Building even a modest emergency fund can also reduce dependence on credit cards when unexpected expenses arise. Families may benefit from reviewing several months of transactions to identify spending patterns that are difficult to recognize from individual purchases. The objective is not necessarily to spend as little as possible but to ensure that income supports both present needs and future financial security.
The Bottom Line
A $100,000 salary remains a substantial income, particularly in Columbus, where the typical household earns considerably less. But rising expenses, family responsibilities, debt, and insufficient savings can leave even six-figure earners feeling financially insecure. The difference between appearing financially successful and actually being secure often comes down to how much money remains after essential obligations are paid.
For Americans wondering why a good salary no longer feels like enough, the answer is rarely explained by one expense alone. It is usually the combined weight of housing, transportation, healthcare, childcare, and other financial commitments. In today’s economy, earning six figures can provide opportunity, but it does not guarantee financial freedom.
Source: U.S. Bureau of Labor Statistics (Consumer Expenditure Survey, 2024; Consumer Price Index, September 2026); Federal Reserve (Economic Well-Being of U.S
News organizations may republish this story with credit. See our guidelines.
Know someone who'd want to read this? Email it to a friend.
Own a Columbus business? 60,000+ page views a month. Ads from $125/month. See ad optionsPlan your weekend with Columbus Times
Get This Weekend in Columbus every Thursday: the best local events, free things to do and family fun, plus each evening's local news. Free, and you can unsubscribe anytime.
Most read this week
- Georgia's 3 Amendments: Which Will Pass, Who's Against Them, and What Happens If They Fail
- Georgia's 3 Constitutional Amendments on the Nov. 3 Ballot, Explained in Plain English
- Early Voting in Columbus Starts Oct. 13: Every Site, the Hours, and What's on Your Ballot
- USDA Awards $3.3 Billion Loan for Georgia Power Plant to Meet Rising Electricity Demand
- Georgia Election Forecast 2026: Who Is Projected to Win Every Major Race?
More stories
 Finance Is Bitcoin a Smart Investment in 2026? What Investors Need to Know Before Buying
 Finance Is $60,000 a Year Enough to Live Comfortably in Columbus, Georgia? Here’s the Breakdown
 Real Estate Homebuilder Confidence Falls to 14-Year Low as Mortgage Rates Hit 7.4% and 43% of Builders Cut Prices
 Real Estate Up to $49,999 for a Down Payment: 4 Programs Helping Columbus Families Buy Their First Home
Comments
Be respectful. No personal attacks, hate speech, spam or anyone's private information. Every comment is reviewed before it appears. Comment rules
No comments yet. Be the first to share your thoughts.