$1 Million Net Worth on an $80,000 Salary: The Blueprint for Your 20s, 30s and 40s
Can You Become a Millionaire Earning $80,000 a Year?
You do not need a six-figure salary, a successful business or a large inheritance to build a net worth of $1 million. For someone earning $80,000 a year, the path to seven-figure wealth can begin with a straightforward strategy: spend less than you earn, invest consistently, avoid expensive debt and give your money enough time to grow.
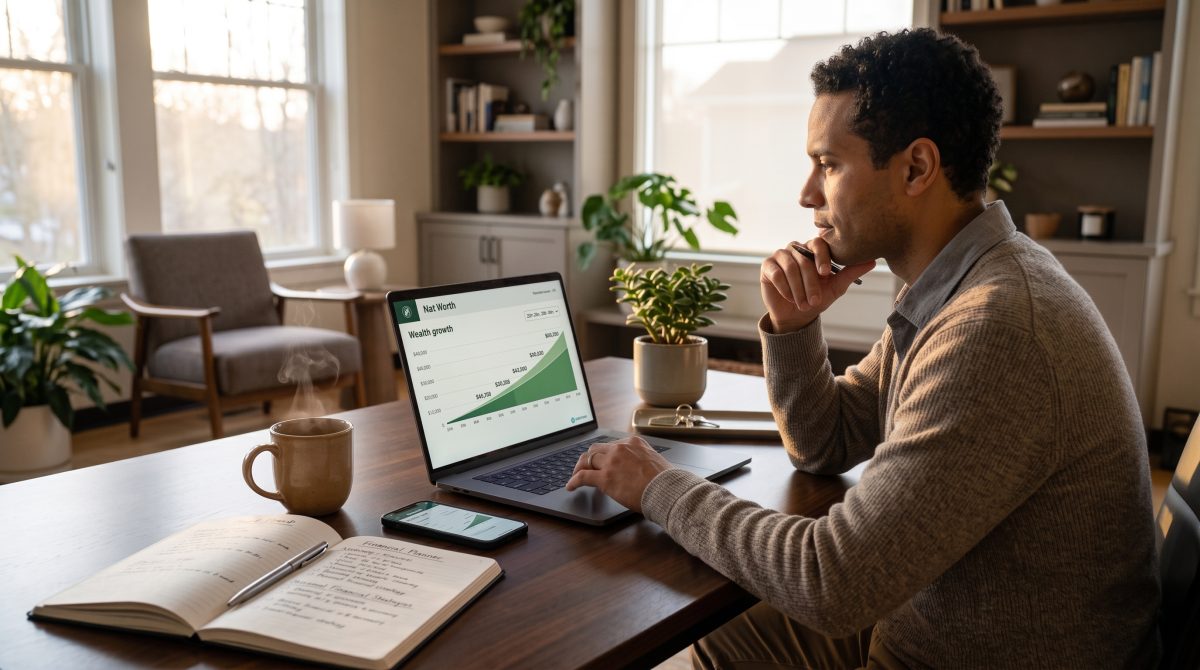
The key is understanding that a million-dollar net worth is not the same as having $1 million in a checking account. Net worth is the value of everything you own minus everything you owe. That includes retirement accounts, brokerage investments, home equity, cash and other assets, less your mortgage, auto loans, credit card balances and other debts.
Someone who owns a home with $250,000 in equity and has $750,000 in retirement accounts and other investments has a net worth of $1 million, assuming those figures account for all other assets and liabilities.
An $80,000 salary provides a reasonable starting point, but the outcome depends on when you start, how much you save, how you invest and whether you avoid financial setbacks that derail your progress.
Here is how the strategy can work across three decades.
Your 20s: Build the Foundation and Let Time Work for You
Your 20s offer one of the most valuable financial advantages available: time. Money invested early has more years to compound, allowing investment returns to generate additional returns over the course of your career.
Suppose you begin earning $80,000 at age 25. Your first priority should be establishing a financial foundation that allows you to invest consistently without relying on credit cards or withdrawing retirement savings whenever an unexpected expense arises.
Start by building an emergency fund. Aim for at least three to six months of essential expenses, keeping the money in an accessible savings account. If your job is unstable or you have substantial financial obligations, you may need a larger reserve.
Next, contribute enough to your employer-sponsored retirement plan to receive the full company match, if one is available. A company match can increase your compensation without requiring you to work additional hours.
From there, work toward saving and investing 15% to 20% of your gross income, including any employer contributions. On an $80,000 salary, that translates to $12,000 to $16,000 annually.
A practical monthly target might look like this:
- Gross monthly income: $6,667
- Retirement and investment contributions at 15%: $1,000
- Retirement and investment contributions at 20%: $1,333
- Remaining gross income before taxes and deductions: $5,334 to $5,667
Your actual take-home pay will be lower after taxes, insurance and other deductions, so housing, transportation and discretionary spending must fit within the amount that remains.
Keep housing costs manageable, avoid financing expensive vehicles and pay off high-interest credit card debt. These decisions matter because every dollar committed to unnecessary interest payments is a dollar that cannot be invested.
For long-term investing, consider diversified, low-cost index funds that provide exposure to a broad range of stocks. Depending on your circumstances and risk tolerance, you may also hold bonds or other appropriate investments. The objective is not to predict which stock will soar next year. It is to build a diversified portfolio and contribute consistently.
Your financial target by age 30: Work toward having your first $75,000 to $125,000 in retirement accounts, investments and other net assets, adjusted for your debt and personal circumstances.
That is an illustrative milestone, not a requirement. Someone who starts later, pays off student loans or supports family members may progress differently.
The important thing is to establish habits that make investing automatic before lifestyle expenses expand to consume every raise.
Your 30s: Increase Investments, Build Home Equity and Grow Your Income
Your 30s are often when financial responsibilities increase. You may buy a home, get married, have children or take on additional expenses. At the same time, you may have more opportunities to increase your earnings through promotions, job changes, specialized skills or additional income.
This is the decade when a strong financial foundation can begin producing substantial results.
If you are still earning $80,000, aim to invest at least 15% to 20% of your gross income. If your income rises, avoid increasing your spending by the same percentage. Direct a significant portion of every raise, bonus or additional payment toward investments and debt reduction.
For example, someone who receives a $5,000 annual raise could direct $3,000 toward additional retirement contributions and investments while using the remainder to improve their standard of living or cover rising expenses.
The numbers become more powerful when contributions increase over time.
Suppose you begin investing $1,000 per month at age 25. By age 35, you will have contributed $120,000. If your portfolio earns a hypothetical average annual return of 7%, compounded monthly, your balance could grow to approximately $173,000.
That figure assumes consistent monthly contributions, a steady return and no withdrawals. Actual investment returns fluctuate, and the market does not deliver a dependable 7% return every year.
Homeownership can also contribute to your net worth, but it should not be treated as a guaranteed investment. A home can build equity through mortgage principal payments and potential appreciation, while property taxes, insurance, maintenance, transaction costs and interest reduce the financial benefit.
If buying a home makes sense for your circumstances, choose a property you can comfortably afford rather than stretching your budget to qualify for the largest possible mortgage.
Consider these priorities during your 30s:
1. Increase retirement contributions. Work toward the annual contribution limits for your workplace retirement plan and individual retirement account when your budget permits. Limits change over time, so verify the applicable figures with the IRS.
2. Invest beyond your retirement account when appropriate. A taxable brokerage account can provide additional flexibility for long-term wealth building once your emergency savings, high-interest debt and retirement priorities are addressed.
3. Pay down expensive debt. Credit card interest and other high borrowing costs can undermine the benefits of investing. Eliminate high-interest balances before taking unnecessary investment risks.
4. Grow your earning potential. Professional certifications, technical skills, leadership opportunities and strategic career moves can increase your income. A higher salary is particularly valuable when you invest the additional money instead of spending all of it.
5. Protect your financial progress. Appropriate health, disability, homeowners or renters, and life insurance coverage can help prevent a single unexpected event from wiping out years of progress. The coverage you need depends on your circumstances and dependents.
Your financial target by age 40: Aim for approximately $300,000 to $450,000 in net worth, depending on your starting point, investment contributions, home equity, debt and financial obligations.
This is an illustrative goal rather than a universal benchmark. You can build substantial wealth without owning a home, and owning a home does not automatically make someone wealthy.
What matters is the value of your assets after subtracting your liabilities.
Your 40s: Turn Decades of Discipline Into Seven-Figure Wealth
Your 40s can be a pivotal decade for wealth accumulation. You may have higher earnings, lower education expenses or more career experience than you did in your 20s. You also have fewer years remaining before traditional retirement age, making consistent contributions especially important.
If you have been investing for 15 or 20 years, your existing portfolio may be large enough that investment growth becomes a meaningful contributor to your net worth.
Consider an individual who reaches age 40 with $350,000 invested and continues contributing $1,500 per month. Assuming a hypothetical 7% annual return compounded monthly, the portfolio could grow to approximately $1.1 million over the next 20 years.
That projection excludes taxes, investment fees and withdrawals. It also assumes the same return throughout the period, which is not how real markets behave. The final value could be substantially higher or lower.
The lesson is not that a 7% return is guaranteed. It is that an established investment portfolio, continued contributions and time can work together to create significant wealth.
During your 40s, review your entire financial picture rather than focusing exclusively on your retirement account.
Calculate your net worth by adding your cash, retirement accounts, brokerage investments, home equity and other assets, then subtracting your mortgage, vehicle loans, credit cards and other outstanding debt.
For example, a household might have the following balance sheet:
Asset or liability Amount Retirement accounts $500,000 Taxable investments $200,000 Home equity $250,000 Cash savings $50,000 Total assets and equity listed $1,000,000 Remaining vehicle and other debts -$0 Net worth $1,000,000
This simplified example illustrates how a household can reach a million-dollar net worth without holding $1 million in cash. It assumes no additional liabilities and treats home equity as the home’s value minus its mortgage balance.
A household with a $300,000 home and a $250,000 mortgage has $50,000 in home equity, not $300,000. Counting the entire property value without subtracting the mortgage would overstate net worth.
If you are approaching your 50s and your investments remain below your target, avoid trying to catch up through speculative stocks, excessive leverage or other high-risk bets.
Instead, calculate how much you can reasonably contribute, review your retirement timeline, eliminate expensive debt and consider whether additional income could accelerate your progress.
Your financial target by age 50: A $1 million net worth is possible for some people following this strategy, but it is not guaranteed. Your result will depend on your starting balance, investment contributions, returns, debts and whether you experience significant financial setbacks.
The Numbers: How Much Must You Invest to Reach $1 Million?
The following examples illustrate how regular investing can contribute to a seven-figure portfolio.
Assume a person starts with no investments and contributes the same amount every month. The projections use a hypothetical 7% annual return, compounded monthly, with contributions made at the end of each month.
Monthly investment Annual investment Approximate balance after 20 years Approximate balance after 30 years $500 $6,000 $260,000 $610,000 $750 $9,000 $391,000 $915,000 $1,000 $12,000 $521,000 $1.22 million $1,250 $15,000 $651,000 $1.52 million $1,500 $18,000 $781,000 $1.83 million
These are approximate mathematical projections, not forecasts or guarantees. They exclude taxes, fees and withdrawals and assume contributions remain constant. Actual investment returns vary from year to year, and inflation reduces the purchasing power of future dollars.
The table reveals an important point: someone who invests $1,000 monthly for 30 years could accumulate more than $1 million under the stated assumptions, even without an initial lump sum.
At an $80,000 salary, that monthly contribution equals 15% of gross income.
If you begin investing in your 20s, you have more time for compounding to work. If you begin in your 30s or 40s, you may need to invest more each month, work longer or combine investments with other assets to reach the same goal.
For a more realistic plan, increase contributions as your salary grows rather than assuming that your income and savings will remain unchanged for three decades.
Five Financial Mistakes That Can Keep You From Becoming a Millionaire
Even a solid salary can disappear without careful financial decisions. These common mistakes can slow wealth accumulation.
1. Buying too much house. A large mortgage, high insurance premiums and rising maintenance expenses can leave little money available for investing. Buy based on your overall financial position, not simply the amount a lender approves.
2. Financing expensive vehicles. Repeatedly taking out large auto loans can divert thousands of dollars from retirement accounts and brokerage investments. Consider the full cost of ownership, including depreciation, insurance, repairs and interest.
3. Allowing lifestyle inflation to consume every raise. Earning $100,000 instead of $80,000 will not necessarily increase your net worth if your expenses rise by the same amount. Save a meaningful portion of every income increase.
4. Waiting for the perfect time to invest. Markets are unpredictable, and attempts to consistently buy at the bottom can lead to missed opportunities. A regular contribution strategy can reduce the temptation to make emotional decisions, although it does not eliminate investment risk.
5. Taking unnecessary investment risks. Concentrating your savings in one company, borrowing to invest or chasing speculative assets can produce large losses. Diversification does not prevent all losses, but it can reduce dependence on any single investment.
What About Inflation?
A million dollars will not have the same purchasing power in 20 or 30 years that it has today.
At an illustrative 2.5% annual inflation rate, $1 million received 30 years from now would have purchasing power equivalent to roughly $477,000 today.
That distinction matters when setting retirement goals. Someone who wants the lifestyle that $1 million can support today may eventually need a higher nominal net worth.
You can address inflation by reviewing your goal periodically, increasing contributions as your earnings rise and evaluating whether your projected retirement assets can cover your anticipated expenses.
Do not assume that reaching a particular number automatically means you can retire comfortably. Your retirement spending, health care costs, Social Security benefits, housing situation and expected retirement age all influence how much wealth you need.
The Bottom Line: An $80,000 Salary Can Be Enough to Build Serious Wealth
Becoming a millionaire on an $80,000 salary is not a matter of finding a secret investment or getting rich overnight. It is about making a series of financially sound decisions and repeating them for years.
In your 20s, establish an emergency fund, avoid high-interest debt and begin investing consistently. In your 30s, increase contributions as your earnings grow and make careful decisions about housing and other major expenses. In your 40s, protect your accumulated assets, evaluate your retirement timeline and keep investing according to a realistic plan.
A person who invests $1,000 per month for 30 years could accumulate approximately $1.22 million at a hypothetical 7% annual return, before taxes and fees. The actual result could be substantially different, but the example demonstrates how regular investing can turn a moderate salary into a potentially substantial portfolio.
The most important variable is not whether you earn $80,000 or $180,000. It is how much of your income you consistently convert into assets that can support your future.
The blueprint is simple: spend less than you earn, invest consistently, avoid unnecessary debt and give your money time to grow.
News organizations may republish this story with credit. See our guidelines.
Know someone who'd want to read this? Email it to a friend.
Own a Columbus business? Reach 40,000+ monthly readers. Ads from $125/month. See ad optionsPlan your weekend with Columbus Times
Get This Weekend in Columbus every Thursday: the best local events, free things to do and family fun, plus each evening's local news. Free, and you can unsubscribe anytime.
More stories
 Finance Is Bitcoin a Smart Investment in 2026? What Investors Need to Know Before Buying
 Finance Is $60,000 a Year Enough to Live Comfortably in Columbus, Georgia? Here’s the Breakdown
 Business Columbus-Area Job Openings: Who’s Hiring and What the Jobs Pay
 Politics Georgia's 3 Amendments: Which Will Pass, Who's Against Them, and What Happens If They Fail